Local Exchange Trading Systems: A Primer
A practical introduction to mutual credit, how a local trading group keeps its books and where community exchange runs into limits.
How a trade works
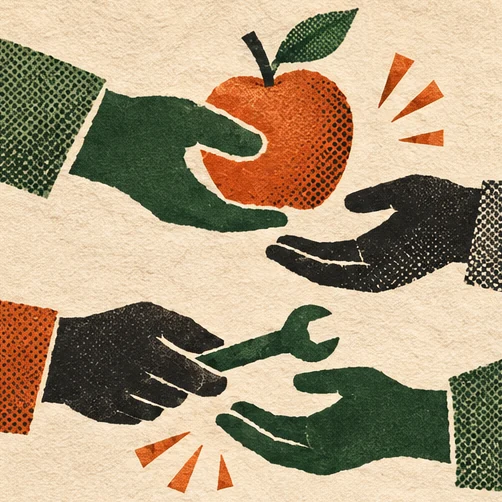
Local Exchange Trading Systems, or LETS, let people in a community buy and sell using balances kept by the group. The units can represent a local currency or another measure the members agree to use. Mutual credit means the balance is created through the exchange.
Say Rosa repairs Sam’s bicycle for twenty credits. The ledger adds twenty to Rosa’s balance and subtracts twenty from Sam’s. Rosa can spend the credit with somebody who has never met Sam. Sam can work his balance back up by making something or offering a service to another member. A group with both positive and negative balances needs enough regular trades for people to spend what they earn and make good on what they owe.
Set up the exchange
Members need a way to list what they offer and what they want. They need accounting that is simple enough to check, a process for joining, limits on negative balances and a way to resolve disputes. The rules should answer who can correct a transaction, what happens when someone leaves and when a member’s balance is visible to other people.
Pricing is another decision. In a time bank, an hour may be the common unit. A mutual-credit group can allow participants to negotiate values. The choice affects which services become available and whether members feel their labor is recognized. Different groups also draw different lines around sharing receipts, publishing contact details and handling trades involving regulated work.
Look at neighboring models
Switzerland’s WIR network, Canada’s early LETS experiments, Ithaca Hours in New York and the Bristol Pound in England are often discussed together. They all tried to support transactions in a defined network or place, using different rules. Printed local currency, business-to-business mutual credit and time banking create different rights and obligations for participants.
Those differences matter when borrowing an idea. An arrangement intended to help businesses clear accounts requires enough suppliers and buyers to make the credits useful. A small neighborhood exchange can grow out of relationships people already have, then run into limits as more strangers participate.
Keep the benefits and limits in view
Trade can put idle skills and goods to use, create relationships and give people another way to meet some needs when cash is tight. Its usefulness depends on participation. An exchange with few listings may leave someone sitting on a positive balance. An unreliable ledger or dispute process can weaken trust. Costs such as rent, taxes and supplies bought outside the group generally still call for money accepted by those parties.
Starting with a narrow set of everyday exchanges gives members a chance to learn what makes the system useful. Look for repeat trading and a balance between different things people need. Those are better signs of health than the number of names in the membership list.